

Best Budget
CREXIN Technologies
- 0.0
- 0.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
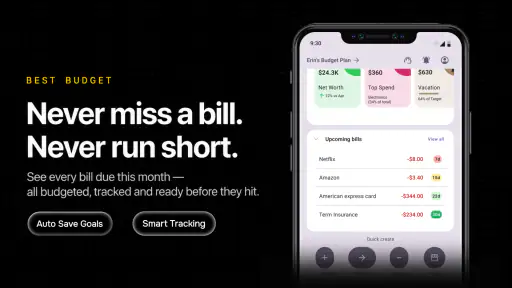
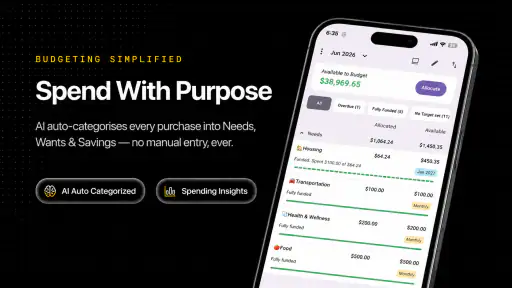
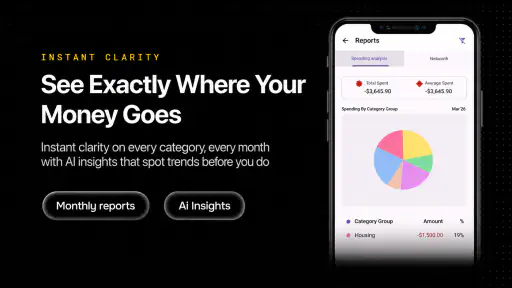
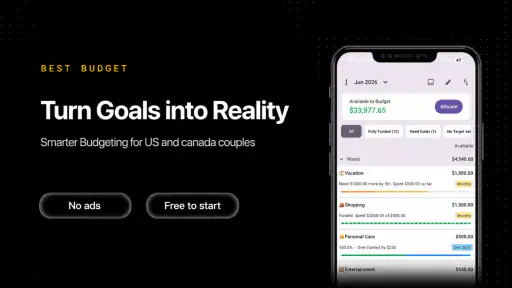
Best Budget Pros and Cons
Pros
- Simple interface makes expense tracking quick and approachable.
- Useful for monitoring spending against a personal budget.
- Helps organize finances without requiring advanced accounting knowledge.
- Clear overview can make recurring spending easier to identify.
- Suitable for users who want a lightweight budgeting companion.
Cons
- May lack advanced reports for detailed financial analysis.
- Manual entry can become time-consuming for frequent transactions.
- Limited customization may not suit complex household budgets.
- Some features may require an upgrade or in-app purchase.
- Data accuracy depends on keeping every expense updated.
 Analysis by All-app
Managing money usually fails for a simple reason: the information is scattered. A bank balance shows what is left, a notes app may contain a few reminders, and a spreadsheet can become too much work after the first week. Best Budget, a finance app from CREXIN Technologies, takes a more focused approach by putting spending, budgets, debt goals, and savings planning in one place. I found its appeal less in flashy presentation and more in the way it encourages a regular money check-in.
The app is free to install, rated for Everyone, and available for devices running Android 8.0 or later. Its current version is 2.1.4, and it has passed the ten-thousand-install mark. Those details make it look like a relatively young, accessible budgeting tool rather than a long-established financial platform. The important question is not whether it can replace a bank app, but whether it can make everyday decisions easier without turning personal finance into another chore.
How Best Budget fits into everyday money management
I’d use this section to focus on the small decisions that make a budget workable: choosing a few clear priorities, then checking whether real spending still fits them as the week unfolds. That approach keeps the app useful even when plans change, and it also makes it easier to judge whether its budgeting routine suits your habits.
A practical starting point for spending awareness
When I use a budgeting app, I do not expect it to make money disappear from my account or negotiate bills for me. I want it to make patterns visible. Best Budget is positioned around that basic but useful job: tracking spending, setting limits, reducing debt, and building savings. That combination gives it a broader purpose than a simple expense diary, because it connects today’s purchase with a longer-term target.
The most useful way to approach it is to begin with a small number of meaningful categories. Rent, groceries, transport, subscriptions, eating out, and debt payments are usually more helpful than creating a separate category for every minor purchase. A detailed system can look impressive but becomes difficult to maintain. Best Budget makes more sense when it is used as a routine rather than as a perfect accounting record.
I would start by recording a normal week instead of immediately trying to redesign an entire household budget. That first pass can reveal whether the problem is frequent small spending, irregular large bills, or simply a lack of separation between essential and optional purchases. Once that pattern is clear, the budgeting and savings side becomes more realistic.
Where its free access matters
Best Budget is free to download, which lowers the risk of trying it. Someone who has never kept a budget can test the workflow without committing money before knowing whether regular tracking fits their habits. That is a meaningful advantage over a paid-first tool, especially for students, people rebuilding their finances, or anyone who only wants a straightforward personal system.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
There are in-app purchases priced from six dollars to ninety-six dollars per item. I would therefore treat the free access as an opportunity to evaluate the core experience, not as proof that every useful function is available at no cost. The sensible approach is to use the free version long enough to understand what it actually helps you do, then judge any optional purchase against a specific need. Paying only makes sense if the added value saves time or helps you follow through.
This distinction is important. A budget app can be inexpensive and still poor value if it takes too much effort to keep updated. Conversely, a paid option can be worthwhile for someone who uses it every day. With Best Budget, the safest buying decision is personal: first establish whether the app becomes part of your weekly routine, then consider whether an in-app purchase improves that routine enough to justify its cost.
A realistic weekly workflow
Imagine a user paid on Friday and wants to avoid reaching the end of the month with no clear explanation for where the money went. On Friday evening, I would review the available amount, assign planned money to essentials, and set a modest limit for flexible spending. During the week, I would record purchases soon after making them rather than relying on memory. On Sunday, I would compare actual spending with the plan and move attention to the category that is drifting.
The debt and savings goals are most useful when treated as separate priorities rather than vague ambitions. For example, a person might keep a small emergency-saving target while making a fixed debt payment. The point is not to create an unrealistic plan that collapses after one unexpected expense. It is to make the next action visible and repeatable.
A less obvious benefit of this workflow is that it turns a budget into a feedback loop. If the grocery limit is repeatedly missed, the answer may not be “try harder.” The category may be too low, shopping may be happening without a list, or household spending may be mixed with personal spending. The app can help expose that mismatch, but the user still has to interpret it.
Useful habits that are easy to overlook
One practical tip is to create categories based on decisions, not just descriptions. “Necessary weekly spending” and “planned personal spending” can be more useful than a long list of merchant types because they help answer whether a purchase fits the plan. This is especially helpful for people who tend to justify each expense individually while losing sight of the monthly total.
A second tip is to use debt goals as a commitment device. Instead of checking debt only when a payment is due, I would review the goal whenever the budget is updated. That keeps debt reduction connected to ordinary spending choices. A small reduction in optional spending becomes easier to understand when it has a visible purpose.
A third insight concerns irregular costs. Annual renewals, seasonal travel, repairs, and gifts can make a monthly budget appear successful until one large bill arrives. I would use the savings side to prepare for those predictable surprises, even if the amount set aside is modest. This is a stronger use of the app than treating savings as whatever happens to remain at the end of the month.
There is also a useful trade-off in keeping the system deliberately simple. If entering every transaction becomes annoying, accuracy will decline. A smaller number of categories, updated consistently, can produce better decisions than a highly detailed plan that is abandoned. Best Budget seems better suited to that sustainable middle ground than to people who want a full financial ledger.
What it can and cannot replace
I would not use Best Budget as a substitute for a bank or card provider. A banking app remains the place to verify balances, review official transactions, and manage accounts. Best Budget is more useful as the planning layer on top: it asks what the money is intended to do, while the bank shows what has actually happened.
It also occupies a different space from a spreadsheet. A spreadsheet offers almost unlimited customization, which is valuable for households with complicated income, shared expenses, investments, or detailed forecasting. The cost is setup and maintenance. Best Budget should appeal more to someone who wants a ready-made budgeting focus without designing formulas and layouts.
Compared with a paper notebook, the app offers a more structured way to connect spending with debt and savings objectives. Paper can be faster for a person who enjoys writing everything down, and it avoids learning another interface. The app becomes the better choice when reminders, organization, and a single place for several financial goals matter more than the simplicity of a page.
Where the experience may create friction
The first limitation is behavioral rather than technical: a budgeting tool is only as useful as the information entered into it. If purchases are recorded late, forgotten expenses can make the remaining budget look healthier than it is. I would recommend a short, regular review instead of waiting for a stressful end-of-month audit.
Another trade-off is the possibility of over-planning. People who already feel anxious about money may turn every category into a restriction. A budget should support choices, not make ordinary spending feel like failure. Best Budget is most helpful when limits are adjusted after observing real behavior, rather than imposed as rigid targets on the first day.
The in-app purchase range also deserves careful attention. Since the app is free to start but includes optional items costing from six dollars to ninety-six dollars each, users should avoid assuming that a purchase is necessary simply because it is offered. I would compare the benefit with a clear question: will this help me track money more consistently, understand my priorities, or save more than it costs? If the answer is unclear, staying with the free access is the safer value decision.
People looking for automatic financial aggregation, investment analysis, shared household controls, or professional-grade reporting may find a dedicated alternative more appropriate. Best Budget’s stated focus is personal budgeting, debt, and savings. That focus can be a strength for a user who wants less complexity, but it also means the app should not be judged as though it were a complete financial-management suite.
Who is likely to get the most value
I think Best Budget is a good match for someone who wants a clear first step. That includes a person whose spending feels uncontrolled, someone trying to build a savings habit, or a user who needs debt to become a visible monthly priority. The free entry point makes experimentation easier, and the Everyone rating keeps it broadly accessible for ordinary personal use.
It may also suit users who have tried spreadsheets and stopped using them because setup was too demanding. A focused budgeting app can remove the temptation to keep redesigning the system. The best results will come from a user willing to spend a few minutes reviewing transactions and adjusting categories honestly.
I would be more cautious about recommending it to a couple who needs synchronized household finances, a freelancer with several income streams, or an investor seeking portfolio tools. Those users may need specialized capabilities beyond a spending-and-goals workflow. Likewise, anyone unwilling to enter or review financial information should skip budgeting apps in general; no interface can compensate for missing records.
For a teenager or young adult learning basic money habits, the app’s Everyone content rating and straightforward financial purpose are reassuring starting points. However, I would still encourage a simple plan rather than a complicated one: track the main spending areas, set one savings goal, and review progress weekly. The goal should be learning control, not producing a perfect financial report.
My value judgement before paying
Best Budget delivers its clearest value when it changes behavior. A person who opens it once, enters a few numbers, and never returns will receive little benefit whether the app costs nothing or includes premium options. Someone who uses it to notice overspending, prepare for irregular bills, and keep debt or savings visible may find the free starting point genuinely useful.
I would not recommend buying an in-app item immediately. First, I would test whether the app fits three habits: recording spending, reviewing the plan, and acting on what the review shows. If those habits are working and a paid option directly removes a recurring obstacle, the purchase may be reasonable. If the problem is motivation or an unrealistic budget, paying more will probably not fix it.
That approach also protects against a common budgeting mistake: confusing more features with better results. The strongest system is the one that can be maintained during a busy week, after an unexpected expense, and when motivation is low. Best Budget has a credible role as a focused companion for that kind of routine, but its value depends heavily on the user’s consistency.
Final recommendation
My overall view is positive but measured. Best Budget is worth trying if you want a free finance app centered on spending awareness, budgets, debt reduction, and savings goals. Its strongest case is for individuals who need structure without the workload of building a spreadsheet. The developer, CREXIN Technologies, presents it as a focused budgeting tool, and the current version gives new users a practical entry point on supported Android devices.
I would recommend starting with a small, honest plan, reviewing it weekly, and using savings goals for predictable irregular costs rather than only emergency leftovers. Keep the categories understandable, and treat any optional purchase as a separate value decision rather than an automatic upgrade. The real test is whether Best Budget helps you make a better money decision before the next purchase.
Skip it if you need advanced account integration, investment management, complex shared finances, or a system that requires almost no manual attention. Choose it if your main need is to see where money goes and give each part of it a job. For that audience, the free access makes the trial low-risk, while the paid options should be considered only after the everyday workflow has proved useful.
Frequently Asked Questions
What is Best Budget, and what can I use it for?
Best Budget is a personal finance app designed to help you organize income, expenses, bills, and savings goals in one place. After reviewing its budgeting workflow, it is most useful for people who want a clearer view of their daily spending and monthly balance. You can categorize transactions, monitor spending limits, and use the available summaries to make more informed financial decisions.
Is Best Budget suitable for beginners who have never used a budgeting app?
Yes, Best Budget is generally suitable for beginners because its main purpose is to simplify money management rather than overwhelm users with complex financial tools. The app’s categories, budget planning features, and expense overview can be understood gradually. However, new users should spend a few minutes configuring income sources, recurring costs, and spending categories so the reports accurately reflect their real financial situation.
Does Best Budget connect directly to my bank account?
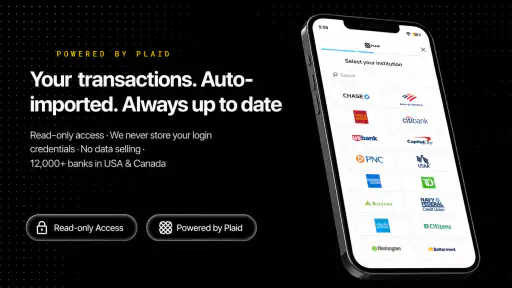
Bank connection options can vary depending on the version of Best Budget, the country where you live, and the financial institutions supported by the app. Before downloading or entering sensitive information, check the current store listing and privacy documentation to confirm whether automatic synchronization is available. If it is not supported, you may need to add transactions manually or import them using the formats offered by the app.
Is my financial information safe when using Best Budget?
Because Best Budget may involve personal financial details, privacy and security should be reviewed before regular use. Check whether the app explains how data is stored, shared, synchronized, and deleted, and confirm whether it provides protections such as device authentication or encrypted connections. Avoid entering banking credentials unless you understand the provider’s security practices and are comfortable with the permissions requested.
Is Best Budget free, or does it require a subscription?
The cost of Best Budget depends on the current version and the platform from which you download it. Some budgeting apps provide a free basic experience while reserving advanced reports, synchronization, unlimited accounts, or additional planning tools for a premium plan. Review the app-store description carefully for subscriptions, trial periods, in-app purchases, and renewal terms before activating any paid feature.


